Public Adjuster Long Island: The Homeowner's Playbook for Protecting Your Property Claim
Key takeaways
- •Public adjusters are licensed to represent policyholders, not insurance companies
- •Carrier scopes commonly miss tear-out, code upgrades, matching, contents, and Additional Living Expense
- •Long Island policies often carry percentage hurricane deductibles of 1% to 5% of dwelling coverage
- •Documenting the date and cause of the loss defeats gradual-damage denials
- •New York caps public adjuster compensation at 12.5% of the recovery
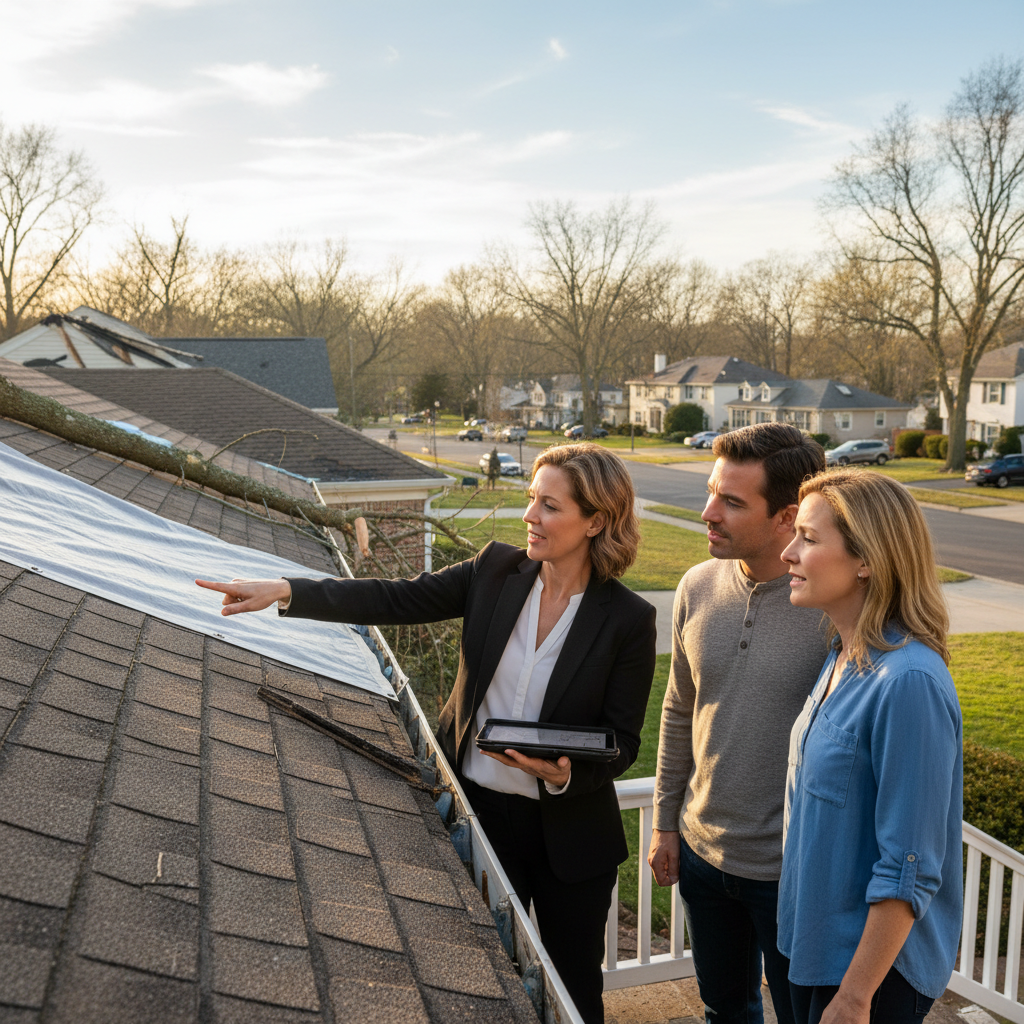
Why "Good Hands" May Not Be Enough When Disaster Strikes Your Home
Introduction: The Rules Have Changed
If you own a home in Nassau or Suffolk County, you likely believe your insurance policy is a safety net. However, the insurance industry has shifted from a philosophy of "pay what we owe" to viewing their claims departments as "profit centers". Driven by consultants like McKinsey & Company, many insurers now use a strategy of Delay, Deny, Defend to minimize payouts to homeowners. Homeowners can verify a public adjuster's license through the New York Department of Financial Services.
This guide reveals the specific tactics used against homeowners and provides actionable steps to protect your biggest investment. Public adjusters are licensed professionals dedicated to representing policyholders in insurance claim negotiations, and they are licensed by the New York Department of Financial Services. They operate on a contingency fee basis, meaning they only get paid if you receive a settlement. Hiring a public adjuster can significantly increase your claim settlement and reduce stress during the claims process, helping you achieve the best outcome. Public adjusters handle both residential and commercial claims, including complex cases, and are skilled in maximizing settlements for their clients.
Understanding Public Adjusters
When disaster strikes your Long Island property, navigating the insurance claims process can feel overwhelming - especially when you're up against an insurance company with vast resources and a team of insurance adjusters working to protect their bottom line. This is where a public adjuster steps in as your advocate, making all the difference in the outcome of your insurance claim.
A public adjuster is a licensed professional who represents you, the policyholder, not the insurance company. Their primary mission is to ensure property owners receive a fair settlement that truly reflects the full extent of their property damage. Whether you're dealing with water damage, fire damage, flood damage, or any other type of property loss, a public adjuster brings deep knowledge of insurance policies, coverage details, and the claims process to the table - helping you uncover hidden damages and issues that might otherwise go unnoticed.
Unlike insurance adjusters who are paid by the insurance company and may be incentivized to minimize your insurance settlement, public adjusters work on your behalf. Their fee structure is typically a percentage of the final settlement, meaning their success is directly tied to securing the maximum payout for you. This alignment of interests ensures that your best interests are always at the forefront, and that your public adjuster is motivated to fight for every dollar you deserve.
Public adjusters provide personalized service tailored to your unique situation. They conduct thorough damage assessments, meticulously document every aspect of your claim, and handle all negotiations with the insurance company. This level of support is invaluable during a tough time, allowing you to focus on recovery while your adjuster manages the complex details of the insurance claims process.
For Long Island homeowners and business owners alike, hiring a public adjuster means having an expert team on your side - one that understands the local market, is aware of the true cost of repairs, and knows how to identify hidden issues that could impact your settlement. From estimating repair costs to ensuring all covered damages are included in your claim, public adjusters work tirelessly to secure a favorable settlement and fair compensation for your losses.
In addition to their expertise in damage assessment and negotiation, public adjusters offer ongoing advice and support, keeping you informed and empowered throughout the process. They help you document your claim, explain your coverage, and represent your interests every step of the way.
Ultimately, hiring a public adjuster can make all the difference in protecting your property and financial future. With their professional guidance, you can be confident that your insurance claim is handled with the care, diligence, and expertise you deserve - ensuring the best possible outcome for your recovery and peace of mind.
---
Part 1: The "Computerized" Lowball by the Insurance Company
The Tactic: Gone are the days when an experienced adjuster walked through your home with discretion to write a fair check. Today, adjusters often rely on software programs like Xactimate to estimate repairs.
- The Problem: These programs are often "generic" and suited for "cookie-cutter" homes, not the custom or older homes common in many Long Island towns.
- The Result: Studies have shown that for high-end homes, estimating software can produce error rates of 20% or more, potentially shortchanging a homeowner by tens of thousands of dollars.
- "Garbage In, Garbage Out": If the adjuster inputs incorrect measurements or low-quality materials into the software, the payout price will be artificially low.
Actionable Step: Never accept the insurance company's printout as the final word. You must demand that the estimate accounts for the specific "market conditions" of Long Island and the actual cost of hiring reputable local contractors, who often refuse to work for the low rates set by Xactimate.
---
Part 2: "Scoping" - The Art of Missing Details
The Tactic: Before a price is put on repairs, the adjuster must "scope" the loss - determining exactly what was damaged. Insurers often use "scoping" tricks to reduce the claim size.
- The "Abandoned Floor": If a water leak ruins wall-to-wall carpeting over a hardwood floor, insurers may argue the wood floor was "abandoned" (useless) and refuse to pay for it, offering only cheap underlayment.
- Ignoring "Waste": Adjusters may calculate the exact square footage of a room but fail to pay for the "waste" material needed to match complex patterns or cuts, leaving you with not enough money to buy materials.
- The Matching Trap: If water damages one wall, they may pay to paint only that wall, leaving you with a mismatched room. A public adjuster fights for the cost to paint the whole room or replace the whole floor to ensure uniformity.
Actionable Step: You need a professional who can "scope" the loss comprehensively. Do not let the adjuster rush the inspection. If they miss the "wood trim on the inside of the windows" or fail to account for moving furniture, your claim is already underfunded.
---
Part 3: The "10 and 10" Profit Skim
The Tactic: When a general contractor fixes your home, they charge for "Overhead and Profit" (O&P) - typically 10% for each, totaling 20% above the cost of labor and materials.
- The Trick: Insurers frequently withhold this 20%, arguing that if you haven't paid it yet, they don't owe it.
- The Reality: Courts have rejected this argument, ruling that "Actual Cash Value" includes this cost. By withholding it, the insurer keeps money that belongs to you in their bank account to earn interest.
Actionable Step: Check your estimate immediately. If "O&P" (Overhead and Profit) is missing or withheld, your insurer is likely underpaying your claim by 20%.
---
Part 4: Coastal Risks (Wind vs. Water)
The Tactic: For Long Island residents near the shore, the "Anti-Concurrent Causation" Clause is a critical threat.
- The Clause: Most policies exclude flood damage. But they go further: if a covered peril (Wind) happens at the same time or in sequence with an excluded peril (Water/Flood), the insurer may deny the entire claim.
- The "Slab" Risk: In catastrophic storms (like the "Slab cases" in Katrina), if a house is washed away, insurers often claim it was all water (excluded) rather than wind (covered), placing the burden of proof on the homeowner.
Water damage can be caused by various sources, including burst pipes, leaking appliances, and storm runoff. Mold damage often arises as a consequence of water damage and can affect indoor air quality and property value. Fire damage claims can involve smoke damage, structural loss, and hidden hazards like soot and electrical issues. Properly handling a water damage claim or water damage insurance claim is crucial to ensure all damages, including secondary effects like mold, are covered.
Actionable Step: You must be able to prove exactly which damages were caused by wind before any water damage occurred. This often requires forensic engineering experts, which a public adjuster can help procure.
---
Part 5: Why You Need Representation
The Strategy: Insurers segment claims based on whether the policyholder has professional representation. Internal documents have shown insurers aim to "reduce the need for attorney [or adjuster] representation" because represented claims result in significantly higher payouts. Insurance companies often have experts working for them, so policyholders should also have experts on their side, such as public adjusters.
- The Disparity: Studies cited in the source suggest represented claimants can recover two to five times as much as those who handle claims alone. Public adjusters handle a wide range of property damage claims, including fire, water, storm, and mold damage, using their expertise in public adjusting to advocate for policyholders.
- The "Good Hands" Trap: Insurers will tell you that you don't need a public adjuster because they will handle the paperwork. This is often a tactic to control the settlement amount and keep it low. Insurance adjusters are trained professionals who use specific tools to calculate the extent of water damage, but the insurance claims process can often move too quickly to uncover the true extent of water damage. Taking steps to prevent further damage and thoroughly documenting it is crucial to support your claim and avoid additional losses.
---
Conclusion
The insurance system is designed to be a "zero-sum game" - every dollar they pay you is a dollar less in profit for them. For a Long Island homeowner, hiring a public adjuster is not just about convenience; it is about having a professional who knows the "playbook" and can fight the "Delay, Deny, Defend" tactics to ensure you get the full funds needed to rebuild. Public adjusters are entitled to ensure policyholders receive the full, fair settlement they are legally or rightfully entitled to, and they help clients avoid settling for less than they deserve.
Ready to protect your claim? Request a free claim review with our licensed public adjusters today.
For official guidance on property insurance and claim rights, visit the New York State Department of Financial Services.
Need Help With Your Claim?
Get a free consultation with our licensed public adjusters.